2024 Gaming Review: Navigating the Growth Dynamics of the Middle East & Africa
16 October 2025•

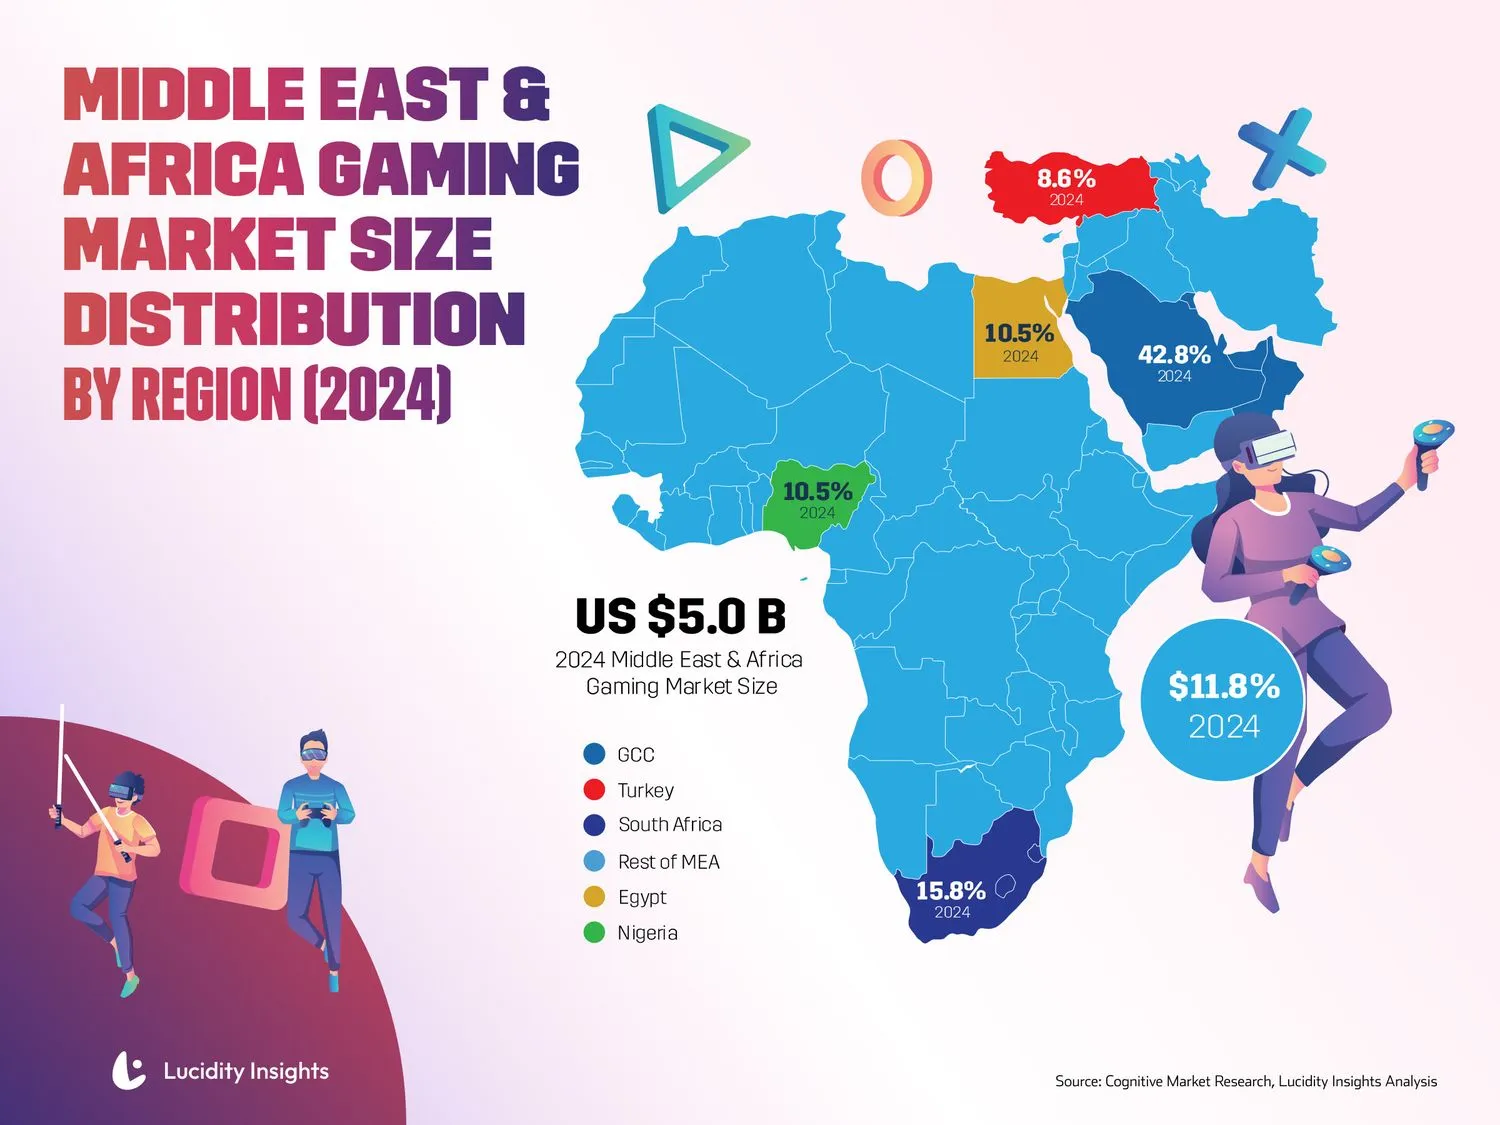
In 2024, the Middle East & Africa (MEA) emerged as one of the fastest-growing gaming regions globally, second only to Asia-Pacific, with total market revenues exceeding US $5 billion. While MEA still represents a smaller slice of the global gaming economy, its momentum—fueled by mobile-first user adoption, government-backed infrastructure investment, and surging venture capital interest—positions the region as a key strategic frontier for publishers, platforms, and investors alike.
Regional Gaming Revenue Dynamics in MEA
The Gulf Cooperation Council (GCC) led regional revenue performance, contributing 42.8% of MEA’s gaming revenues. Saudi Arabia and the UAE remain the primary drivers, supported by high smartphone penetration and flagship projects like Riyadh’s Qiddiya Gaming and ESports District and Dubai’s X-Stadium. These top-down investments continue to foster premium gaming experiences and immersive eSports ecosystems. However, the GCC’s dominance is investment-led rather than user-scale driven. With a combined population of roughly 60 million across all member states, the gamer base remains relatively limited. Instead, the region’s strength lies in high ARPU (average revenue per user), advanced console and PC infrastructure, and a strong culture of microtransactions, subscriptions, and event spending.
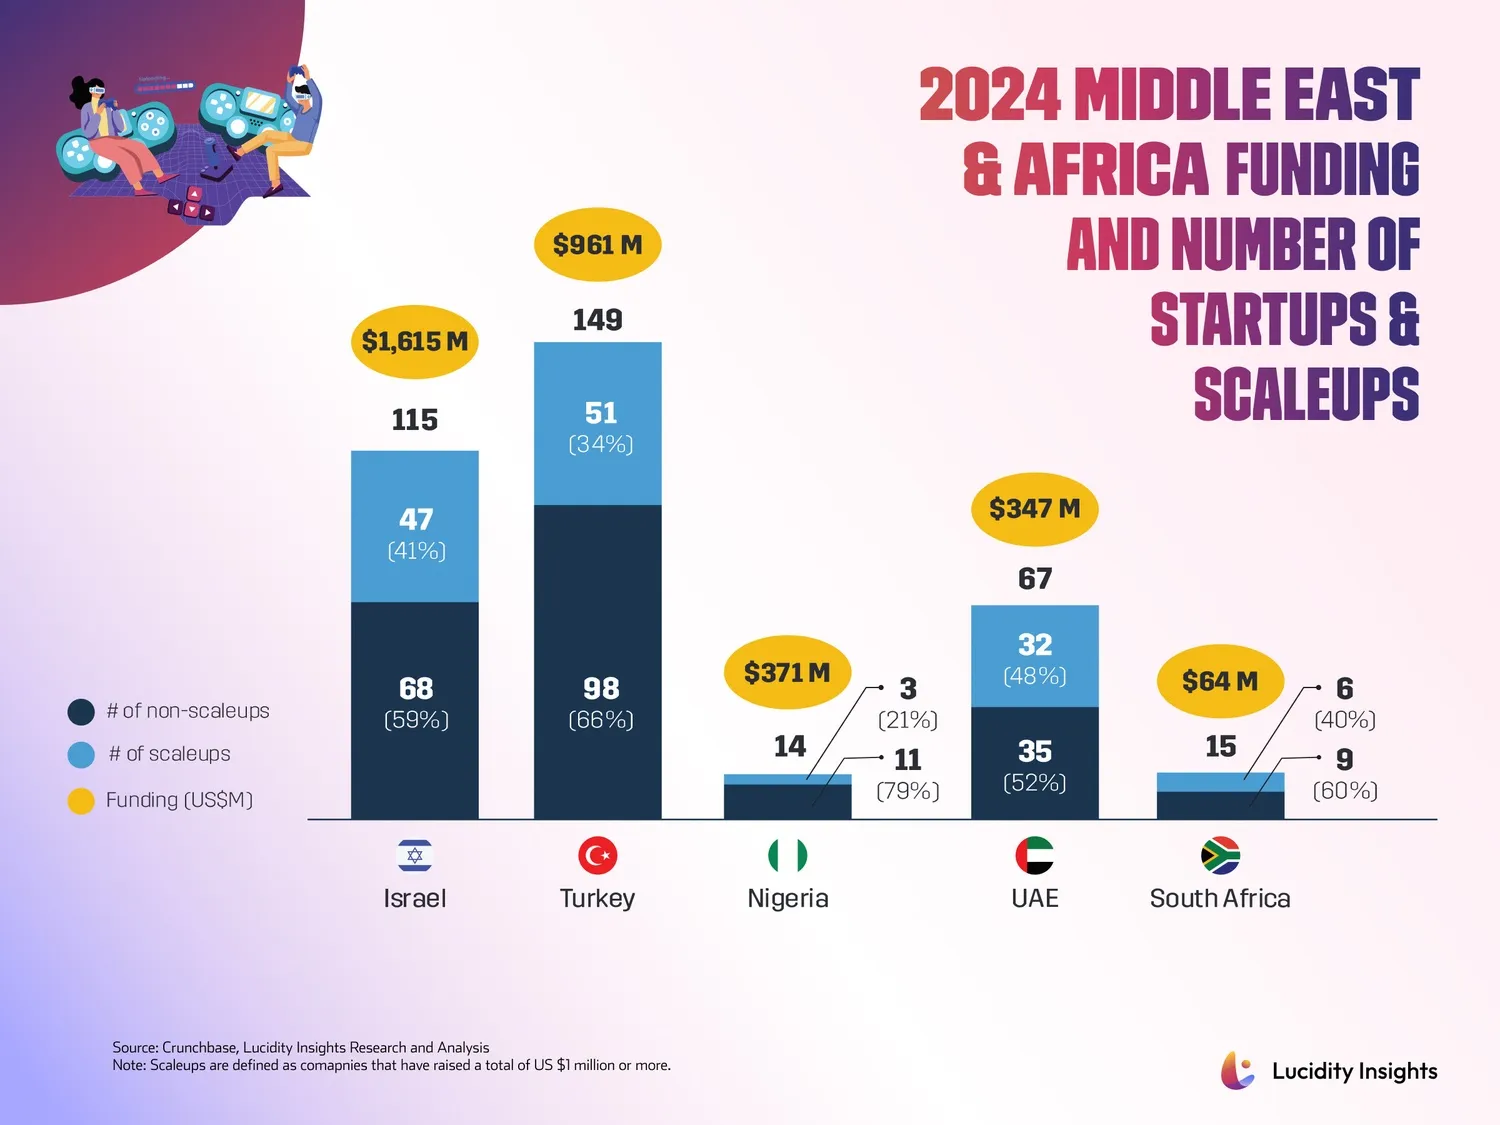
South Africa, contributing 15.8% of MEA revenues, is developing into a regional powerhouse. Urban youth adoption, a growing eSports scene, and the rollout of high-speed internet are fueling consumer momentum. Yet, with only US $64 million in venture funding raised, South Africa remains undercapitalized relative to its market potential.
Frontier markets across North and Sub-Saharan Africa, including Kenya, Morocco, and Algeria, accounted for 11.8% of regional revenues. While fragmented, these markets represent important scale opportunities for mobile-first formats as device access and affordability steadily improve.
Turkey’s share of MEA gaming revenues declined to 8.6% in 2024, continuing a downward trend. While Turkey remains home to standout companies and the region’s highest number of gaming scaleups, it faces market saturation and slowing platform investment—suggesting a shift from high-growth frontier to a more mature, competitive ecosystem.
INVESTMENT LANDSCAPE: Leading Markets & Investors
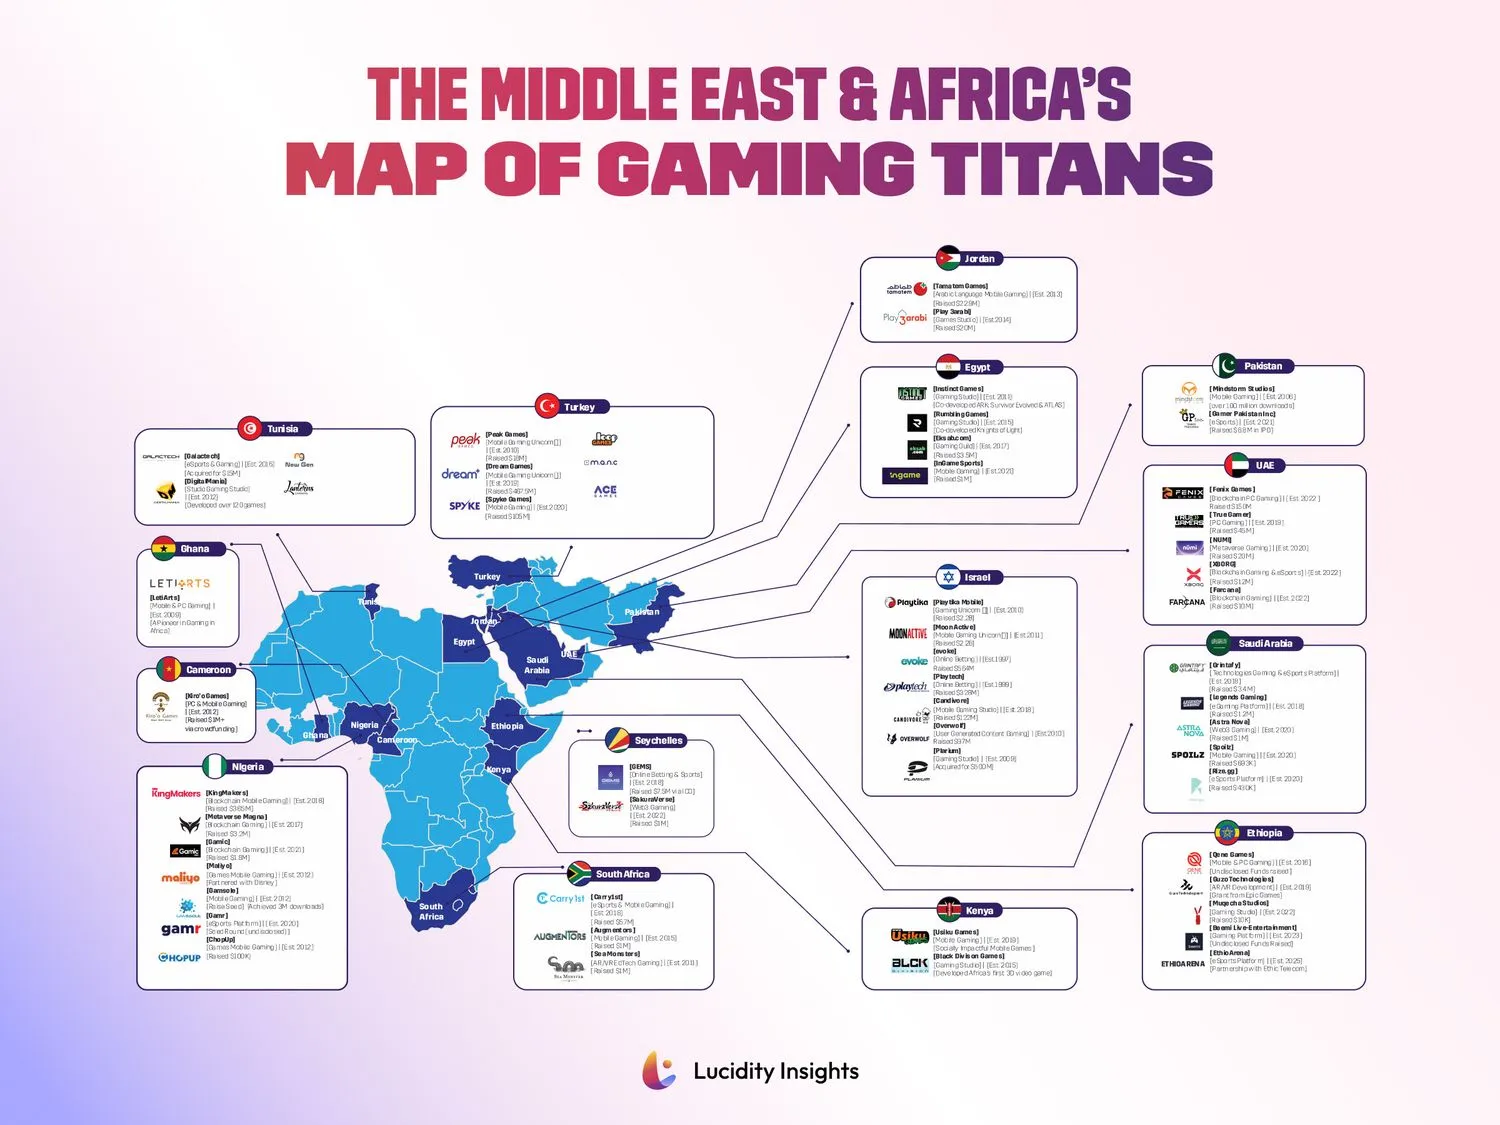
MEA gaming startups collectively attracted US $3.416 billion in venture funding in 2024, though this capital was heavily concentrated. Israel alone accounted for nearly 47% of the total, raising US $1.615 billion. This reflects Israel’s status as a global innovation hub with deep-tech specialization, institutional capital depth, and well-established paths to IPO and secondary exits. Key players like Playtika and Moon Active continue to anchor Israel’s dominance in the sector.
Turkey followed with US $961 million, largely flowing into later-stage ventures like Dream Games and Spyke Games. While investor confidence remains strong, the market’s maturity signals potential headwinds for early-stage entrants seeking to scale.
In Nigeria, US $371 million was raised, driven primarily by a handful of megadeals including KingMakers in digital sports entertainment. Nigeria stands out as Africa’s leading gaming investment destination, though funding remains highly concentrated among select players, with infrastructure challenges still posing barriers to broader scale.
The UAE secured US $347 million in 2024, with notable deals including Fenix Games and True Gamers. Much of this investment aligns with national digital economy strategies and an ambition to position the UAE as a regional eSports and gaming hub.
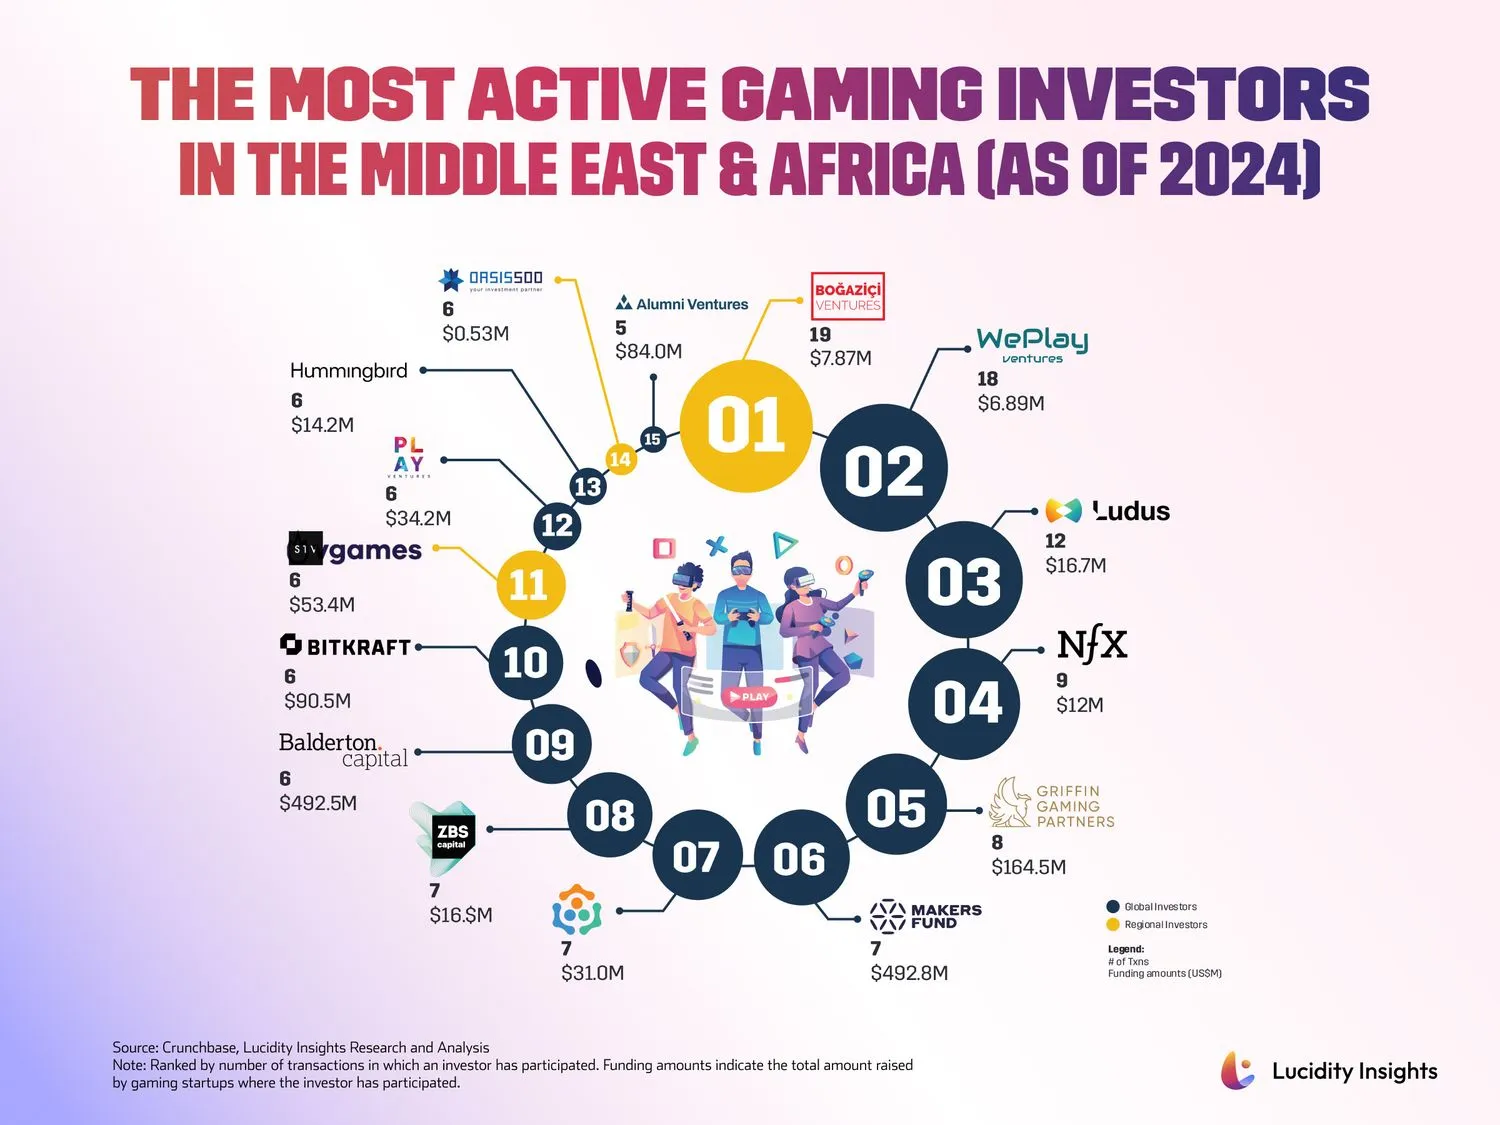
Leading global investors such as Makers Fund, Balderton Capital, and Griffin Gaming Partners were among the most active backers in the region, primarily focusing on later-stage deals. Makers Fund and Balderton Capital alone contributed nearly US $1 billion, highlighting the magnitude of global capital concentrating into fewer, more mature gaming ventures.
In contrast, regional investors, including Boğaziçi Ventures, vgames, and Oasis500 played pivotal roles in early-stage funding and talent development. Boğaziçi Ventures led with 19 transactions, though with a cumulative investment value of US $7.87 million, reflecting the smaller ticket sizes typical of seed and Series A rounds.
Mobile-First Momentum & Market Dynamics
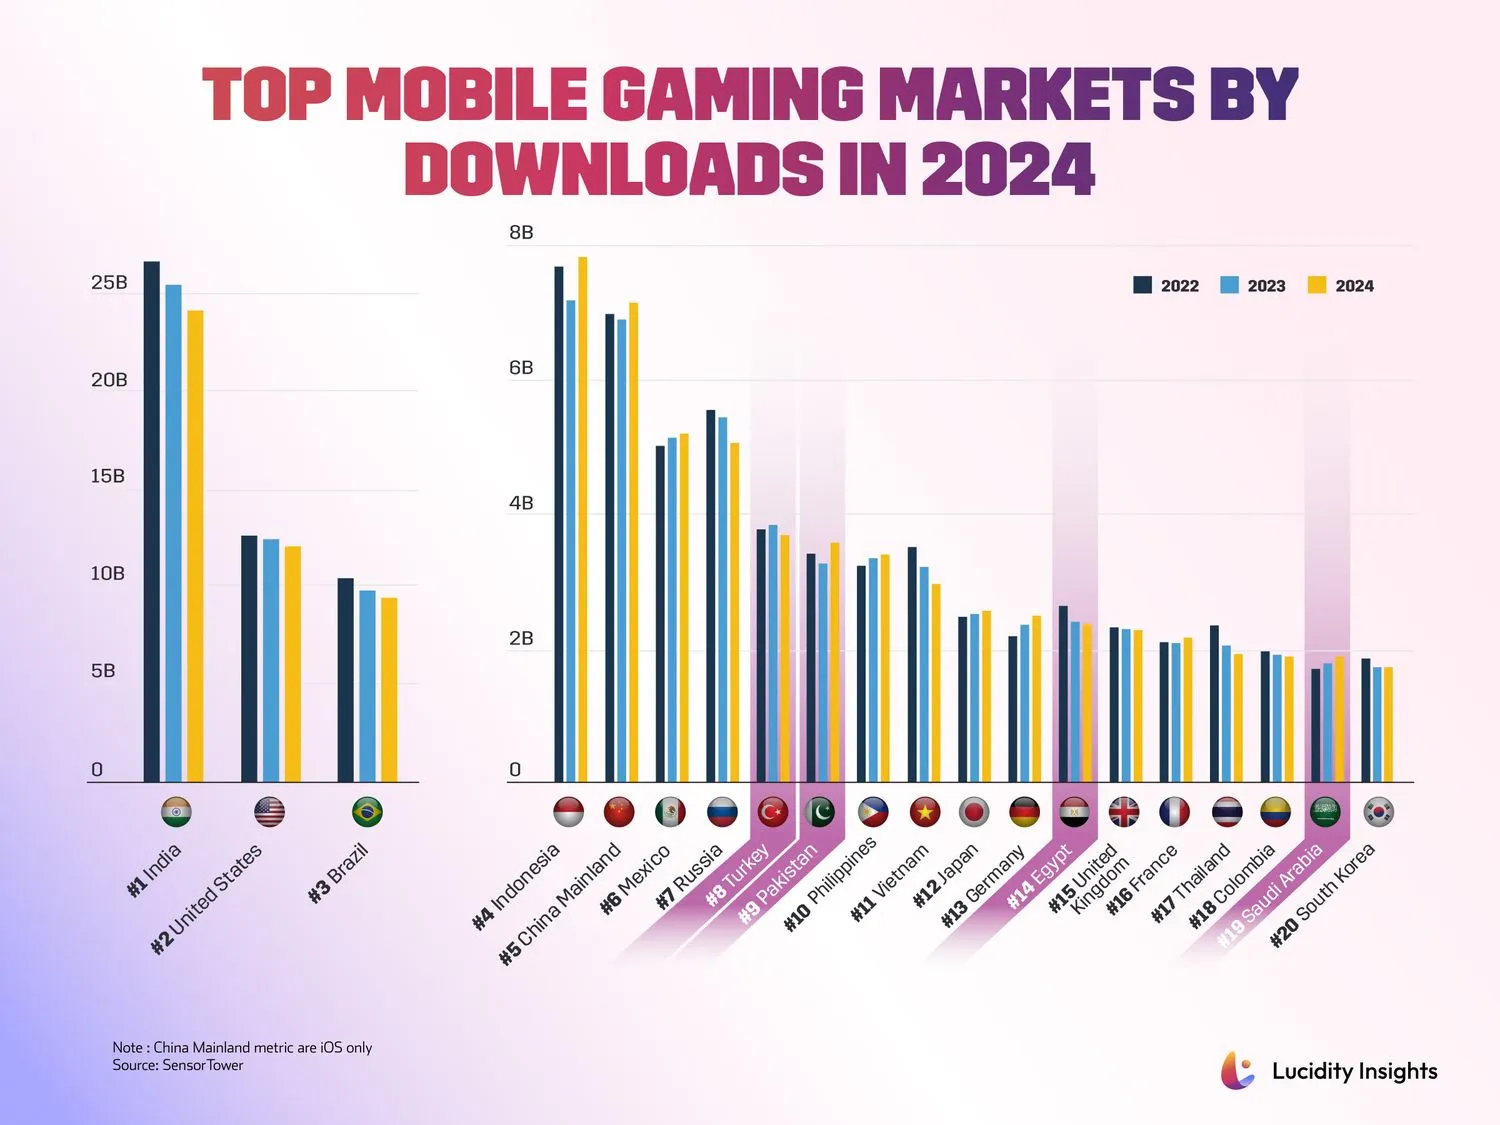
Mobile gaming continues to drive user acquisition across MEA. Turkey, Egypt, and Saudi Arabia all ranked among the world’s top 20 countries for mobile game downloads in 2024. Despite a global softening in downloads, Saudi Arabia bucked the trend, reinforcing its position as a mobile-first market and signaling strong growth potential for user engagement.
MEA Gaming Market Outlook: A Region on the Rise
With a projected CAGR of 9.3% through 2033, the MEA gaming market is on track to more than double in size. This growth will be powered by mobile-first expansion, strategic investment in infrastructure, and the rise of homegrown studios and eSports platforms. As investor attention begins to broaden beyond Israel and Turkey toward underpenetrated markets in Africa and the GCC, the MEA region is poised to play a larger role on the global gaming stage—offering new audiences, creative innovation, and high-growth potential for the decade ahead.
Get a round-up of the biggest gaming trends, startup breakthroughs, and investment opportunities across the Middle East and Africa in 2025, by downloading our latest Special Report, “MEA Gaming Review 2025”.